 Australia
 USA
 Canada
 Ireland
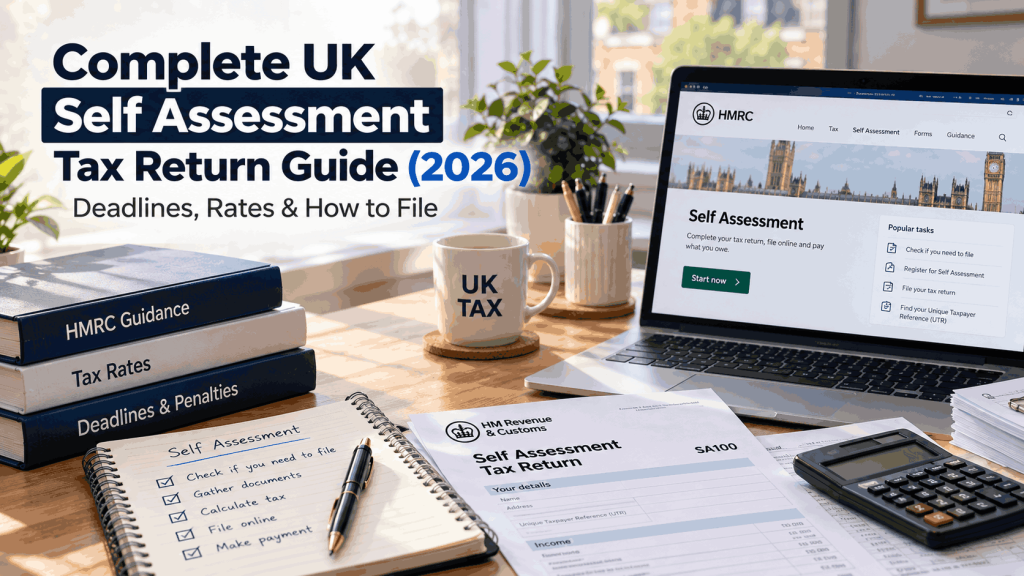

Self Assessment is HMRC’s system for reporting income and gains not fully taxed at source. It applies to sole traders, landlords, company directors with untaxed income, people receiving dividends, and anyone else whose tax position cannot be handled entirely through PAYE. This guide is for individuals who need to complete a return for the 2025/26 tax year.
The 2025/26 tax year closed on 5 April 2026. The deadline for filing a self-assessment tax return is 31 January 2027. Making Tax Digital also started affecting sole traders and landlords from April 2026, adding a layer of compliance to what was already a process many people find harder than it needs to be.
This guide covers the complete 2025/26 self-assessment cycle: whether you need to file, every relevant deadline, what happens if those deadlines are missed, how to register, what documents to gather, how online filing works, the tax rates that apply to this return, and how payment works, including payments on account.
What Is a Self Assessment Tax Return?
Self Assessment is HMRC’s system for collecting Income Tax when it hasn’t necessarily been fully deducted at source. When income comes through employment covered by PAYE, HMRC calculates and deducts tax automatically.
It is a backward-looking system‚ and you calculate and report the accounts for the previous tax year‚ which runs from 6 April to 5 April.
To file‚ simply complete the main SA100 form and any additional schedules needed for your sources of income․
- SA102: Employment income‚ and director’s pay
- SA103S / SA103F: Self-Assessment: Sole trader business profits (short/full schedule)
- SA105: property income and rent․
- SA108: Gains on sales of assets‚ shares‚ property․
Business expenses are deducted when you work out your profit. HMRC then applies your Personal Allowance and reliefs to calculate your tax liability or refund.
Who needs to file a self-assessment tax return for 2025/26?
You may need to file a Self Assessment tax return if you have income or gains that are not fully taxed through PAYE or another HMRC process. Whether you need to file depends on your circumstances and the type and amount of income you received.
You Must File If You:
- Earned more than £1,000 in gross self-employed income: If your gross trading income exceeds the £1,000 trading allowance threshold, you may need to register for Self Assessment and report your income to HMRC. The rules depend on your circumstances, so check HMRC’s current guidance if you are unsure whether you need to file. The threshold applies to gross income before allowable expenses, not net profit.
- Are a partner in a business partnership: A partnership normally submits an SA800 partnership return. In contrast, each partner reports their share of the partnership income on their own Self Assessment return.
- Are a company director: Being a director does not automatically mean you must file a Self Assessment tax return. You may need to file if you receive taxable income that must be reported, such as certain dividends or other untaxed income, or if HMRC sends you a notice to file.
- Have rental or property income: Property income has specific reporting rules. The £1,000 property allowance may apply in some circumstances. If your property income exceeds £2,500 after allowable expenses, or exceeds £10,000 before allowable expenses, you generally need to report it through Self Assessment. Rules can differ depending on your circumstances.
- Received untaxed dividend or investment income: Dividends above the £500 allowance may be taxable. Depending on the amount and your circumstances, HMRC may require you to report this through Self Assessment or may collect the tax through your PAYE code.
- Have Capital Gains Tax to report: If your taxable gains exceed the £3,000 annual exempt amount for 2025/26, you may have Capital Gains Tax to pay or reporting obligations. Depending on the type of disposal and your circumstances, gains may be reported through Self Assessment using SA108 or through HMRC’s separate Capital Gains Tax reporting service․
- Received overseas income: Non-UK pensions, overseas remote contracting income, or foreign investment dividends.
Who May Not Need to File a Self Assessment Tax Return?
- PAYE Earners Over £100k / £150k: HMRC removed the requirement to file based solely on high PAYE income. If tax was deducted at source for the whole year and there’s no other untaxed income‚ there’s no need to file․
- Child Benefit Recipients Under £60‚000: The High Income Child Benefit Charge applies where adjusted net income exceeds £60,000, with the full charge reached at £80,000. In qualifying circumstances, HMRC can collect it through the PAYE tax code rather than Self Assessment.
Self Assessment Tax Return Filing Deadlines for 2025/26
The following deadlines apply specifically to the 2025/26 return․
| Requirement | Deadline |
| Tell HMRC you need to register | 05-Oct-26 |
| Paper Self Assessment return | 31-Oct-26 |
| Online return if collecting eligible tax through PAYE code | 30-Dec-26 |
| Online Self Assessment return | 31-Jan-27 |
| Pay balancing tax due | 31-Jan-27 |
If registration happens after 5 October 2026, HMRC may issue notice requiring filing within 3 months of the date of that notice‚ but payment is still due by 31 January 2027 in all cases․
Why file your return early? Filing before January can give you more time to review your figures, correct errors, understand your tax liability and arrange payment. If you make payments on account, filing earlier can also help you understand how much may be due in January and July.
What Happens if You Miss the Self Assessment Deadline?
Late Filing Penalties
HMRC can impose penalties on late-filed returns‚ whether or not tax is actually owed․
- £100 immediately upon missing the deadline
- £10 per day after 3 months‚ with a maximum amount of £900
- After 6 months: a further 5% of tax due or £300‚ whichever is greater
- After 12 months: 5% of amount due or £300‚ whichever is greater
Late Payment Penalties
- 5% unpaid tax penalty‚ after 30 days
- An additional 5% after 6 months
- A further 5% after 12 months
Interest on Unpaid Tax
HMRC charges interest on any outstanding amounts from the day after the payment is due. The rate can change, so it’s best to confirm the current figure through HMRC’s guidance rather than a fixed percentage in a third-party article.
You can also read Self Assessment deadlines
Common Self Assessment Mistakes to Avoid
Most errors made by taxpayers filling in Self Assessment returns are often a result of incomplete records‚ confusion between tax years‚ and even simply overlooking something about income‚ rather than any deliberate omission․
Common mistakes include: leaving out a source of income (rental income, savings interest and dividend income are frequently missed)‚ entering figures for the wrong tax year, claiming expenses that are not allowable under HMRC’s rules, mixing personal and business expenditure, forgetting pension contributions or Gift Aid where those reliefs apply, overlooking payments on account from the prior year, and submitting without reviewing the HMRC calculation before confirming.
For a more detailed breakdown, Aone’s separate article on common Self Assessment mistakes covers each issue in full. Using that as a standalone resource avoids reproducing the same content here and protects the depth of both pages․
How Is Making Tax Digital Changing Self Assessment in 2026?
Making Tax Digital for Income Tax is already live for some taxpayers from April 2026, but it does not replace the requirement to complete the 2025/26 Self Assessment return. The rollout is phased by income level.
| Qualifying income on return | MTD start date |
| Over £50,000 on the 2024/25 return | 06-Apr-26 |
| Over £30,000 on the 2025/26 return | 06-Apr-27 |
| Over £20,000 on the 2026/27 return | 06-Apr-28 |
Qualifying income is gross income from self-employment and property‚ before deducting expenses and tax‚ not net profit․
The 2025/26 return also affects the next MTD threshold. If the taxpayer has self-employment and property income of more than £30‚000 on their 2025/26 return, they will need to join MTD from 6 April 2027․ HMRC has confirmed that the Self Assessment return for the year before MTD must still be done in the usual way․
What Does Making Tax Digital Require?
Making Tax Digital for Income Tax does not simply replace the Self Assessment tax return. Taxpayers within the MTD rules generally need to keep digital records, use compatible software and send quarterly updates to HMRC, followed by an end-of-period process and final tax return. The requirements depend on whether the taxpayer falls within the relevant MTD income threshold and rules.
How to Register for Self-Assessment and Get a UTR
First-time filers must register with HMRC before submitting a return. The deadline to tell HMRC you need to register for 2025/26 is 5 October 2026.
When registering‚ HMRC will send you a Notice to File‚ and a Unique Taxpayer Reference (UTR) number‚ which must be stored safely, as this number will be needed on all future returns․ HMRC uses this UTR number to distinguish your Self Assessment record
Taxpayers who previously filed returns and then stopped may need to reactivate rather than register from scratch. Creating a duplicate registration can cause administrative delays and complications with HMRC’s records.
Processing times vary, so the expected UTR delivery window is best confirmed against HMRC’s current service guidance at the point of registration rather than a fixed number of days quoted elsewhere․
Documents You Need for Your Self Assessment Tax Return
Collecting documents before you start the return saves time. What is needed depends on the income sources․
Every taxpayer will need:
- National Insurance number
- Unique Taxpayer Reference
- Government Gateway login details
Based on the situation, you may also need:
- P60 and P45 for any income from employment during the year
- P11D for benefits in kind
- Self-employment income and expense records, including invoices and receipts
- Bank statements for the tax year
- Rental income and property expense information
- Dividend vouchers or statements
- Savings interest information
- Details of pension income and State Pension entitlement
- Foreign income documentation
- Records of all capital asset disposals
- Pension contribution records
- Gift Aid payment records
- Student Loan information if applicable
- Evidence of the tax already paid
On record retention: self-employed business records must generally be kept for at least five years after the 31 January filing deadline for the relevant tax year. Although different periods apply to personal tax records that are not related to the business․ The five-year rule applies specifically to business records, not as a blanket requirement for all taxpayers․
How to file a Self-Assessment Tax Return Online
In guidance issued by HMRC‚ published in September 2026‚ about 97% of all Self-Assessment returns are filed online via HMRC’s Government Gateway system․
Step 1: Sign in to your HMRC account
Log in to your Government Gateway account․ If you’re signing in for the first time through Government Gateway to Self Assessment, identity verification will be required before access is granted.
Step 2: Verify your personal information
Before entering any numbers, your return page lists your address, contact details, and the tax year. The HMRC system specifies which supplementary pages apply to your circumstances.
Step 3: Enter your income
Income from employment‚ self-employment‚ partnerships‚ property‚ dividends‚ savings‚ pensions‚ foreign income and capital gains must all be declared‚ as relevant․ All income streams are included at this point in the process․
Step 4: Add Expenses‚ Allowances and Reliefs
Only deductible expenses under HMRC rules are claimable․ This section also includes any pension contributions‚ Gift Aid payments and other reliefs‚ which may be claimed․
Step 5: Review Your Tax Calculation
HMRC’s system will then generate your tax calculation․ You should carefully check your tax calculation to see whether there are any omitted income sources, tax already deducted through PAYE, payments on account already made, available reliefs, and whether a repayment may be due․
Step 6: Check your return and submit
The declaration states that the information is true and places a legal responsibility on the taxpayer to provide accurate information․
Step 7: Save Your Confirmation and Records
HMRC will send a submission reference once it accepts the return. Keep that reference with a copy of the return, the tax calculation, and all supporting documents.
Need Help With Your Self Assessment Tax Return?
Get professional support with preparing, reviewing and submitting your UK Self Assessment tax return.
Self Assessment Tax Return Calculation Example
The following scenario is a simplified example․ Your actual tax will vary depending on your circumstances‚ and where you live in the UK for income tax․
Alex‚ a sole trader‚ is a resident of England․ In the tax year 2025/26‚ he had self-employment turnover of £45,000․ His allowable business expenses were £8,000․ His bank interest was £500․
- Gross business income: £45‚000
- Less allowable expenses: £8‚000
- Business profit: £37‚000
Adding the £500 interest gives total income of £37,500․ Less the £12,570 Personal Allowance leaves £24,930 taxable at income tax rates․ Class 4 National Insurance may apply to profits above the relevant threshold. The amount payable depends on the applicable rates and the taxpayer’s circumstances.
In practice, it may vary depending on whether pension contributions, Gift Aid payments, or payments on account from the previous year are involved. This example shows the basic structure. A return covering multiple income sources, capital gains, or property income will carry additional calculations and may interact with different tax rates.
This is a simplified illustration only. Your actual tax liability can differ depending on your income, allowances, reliefs, National Insurance position and other circumstances.
Self Assessment Tax Rates for 2025/26
Income Tax Rates: England, Wales and Northern Ireland
Personal Allowance: £12,570
The allowance reduces by £1 for every £2 of income over £100,000.
| Tax band | Taxable income after allowances | Rate |
| Basic | Up to £37,700 | 20% |
| Higher | £37,701 to £125,140 | 40% |
| Additional | Over £125,140 | 45% |
Scottish Income Tax Rates
Savings and dividend income continue to use UK-wide rates for Scottish taxpayers. All other income falls under the following bands:
| Band | Income range (with standard Personal Allowance) | Rate |
| Personal Allowance | Up to £12,570 | 0% |
| Starter | £12,571 to £15,397 | 19% |
| Basic | £15,398 to £27,491 | 20% |
| Intermediate | £27,492 to £43,662 | 21% |
| Higher | £43,663 to £75,000 | 42% |
| Advanced | £75,001 to £125,140 | 45% |
| Top | Over £125,140 | 48% |
Dividend Tax
Dividend allowance for 2025/26: £500
| Taxpayer band | Rate |
| Basic rate | 8.75% |
| Higher rate | 33.75% |
| Additional rate | 39.35% |
The rates below apply to the 2025/26 tax year covered by this guide. Some tax and dividend rates changed from 6 April 2026 for the 2026/27 tax year, so do not apply 2026/27 rates when calculating your 2025/26 Self Assessment liability.
Capital Gains Tax
Annual exempt amount for 2025/26: £3,000
Gains above the exempt amount are taxed at 18% (basic rate) or 24% (higher and additional rate) for most individuals, depending on the applicable rate band and the type of asset involved. Specific rules apply to certain reliefs and asset classes.
National Insurance for Self-Employed People
Class 4 NIC rates for 2025/26:
- 6% on profits over £12,570 up to £50,270
- 2% on profits above £50,270
Compulsory Class 2 liability ended on 6 April 2024. Eligible self-employed people can have Class 2 treated as paid for National Insurance record purposes. Those with profits below the relevant threshold may choose to make voluntary Class 2 contributions to maintain their NI record.
How to pay your Self-Assessment Tax Bill
Filing the return and paying the resulting Self-Assessment bill are separate. Filing a return does not automatically result in payment․
Balancing Payments
The balancing payment for the 2025/26 tax year is usually due by 31 January 2027‚ and it is the amount left after deducting PAYE tax‚ payments on account and other credits from the total tax liability․
HMRC accepts payment through several methods. The current list of available options is best confirmed through GOV.UK directly, as what is available can change.
Payments on Account
Payments on account are advance payments towards the tax liability for the following year‚ made in two equal installments ‚ usually half of the last year’s relevant tax liability․
They are generally required unless the previous year’s liability was under £1,000, or more than 80% was already collected outside Self Assessment.
Key dates for a return in 2025/26 include:
- Balancing payments for 2025/26: 31 January 2027
- First payment on account towards 2026/27: 31 January 2027 (if required)
- Second payment on account towards 2026/27: 31 July 2027
The payment on account made on 31 July 2026 was the second payment on account for 2025/26. It counts towards this year’s tax and reduces your balancing payment due 31 January 2027.
Do You Need an Accountant for Your Self Assessment Tax Return?
Many people file simple returns without professional help. If you have a single source of self-employment income, clean records, and no unusual reliefs or gains, self-filing is realistic for most people.
Professional assistance tends to become a greater benefit when there are several sources of income to combine or when the tax return involves rental property‚ capital gains‚ foreign income‚ reliefs with complex conditions‚ or correcting mistakes from earlier tax years․ MTD obligations also increase the burden of further compliance‚ demanding quarterly reporting as well as the annual return․
The return is also a planning opportunity to make use of payments on account‚ classifying expenses properly‚ and dealing with other income․ This will affect not only how much tax is due‚ but when it is actually payable․ An accountant who reviews the return before submission, rather than simply filing whatever figures are presented, tends to identify issues that would otherwise go unnoticed.
If your 2025/26 return involves multiple income sources, property income, dividends, capital gains, foreign income or other complex circumstances, professional support can make the preparation and review process easier. Aone Outsourcing Solutions provides Self Assessment tax return preparation, review and submission support for UK clients.
Getting Your 2025/26 Return Right
The 2025/26 tax year ended on 5 April 2026‚ and the online filing deadline for the tax year is 31 January 2027․ Filing sooner eases pressure on payment‚ allows earlier review of the figures‚ and could allow extra time to arrange payments to pay the tax liability‚ or to adjust payments on account where the liability differs from the prior estimates․
Getting the figures right, applying the right rates, using the correct reliefs, knowing when you make your payment in January and July 2027, and reporting your position correctly on the return depends on having the right records in place before you start. If your return involves complexity beyond a single income source, If you need support preparing your 2025/26 Self Assessment tax return, Aone Outsourcing Solutions can help with return preparation, review and submission.
Frequently Asked Questions
How long does it take to complete a Self Assessment tax return?
There is no reliable universal figure. A simple return with one source of income and good records moves quickly through the process․ A complex return that includes self-employment‚ rental or property income‚ dividends‚ and capital gains‚ with inadequate records‚ is a different matter․
Where do I send my Self Assessment tax return?
Most returns are now filed online․ For paper SA100 returns, HMRC’s current address for UK residents is: Self Assessment, HM Revenue & Customs, BX9 1AS, United Kingdom․ Taxpayers outside the UK use a separate Newcastle address specified in the current HMRC instructions․ Confirm the correct address on GOV.UK before posting, as HMRC addresses can change
Do I need to declare my State Pension or Universal Credit?
State Pension payments are taxable, so if you usually file a Self Assessment return‚ you will need to declare your entitlement․ Universal Credit payments are not taxable and do not need to be declared․
Do company directors have to complete a Self Assessment tax return?
A director may need to file a return‚ if dividends or other untaxed income are taxable on the director personally‚ or otherwise‚ or HMRC may issue a formal notice․ However‚ there is no duty on an individual simply because they are a director․
How do I amend my Self Assessment tax return after submitting it?
HMRC allows changes to be made within 12 months of the filing due date․ For example‚ a 2025/26 return filed by the normal 31 January 2027 due date can be amended until 31 January 2028․ For online returns‚ the amendment normally requires a wait of around 72 hours after the original submission before an amendment can be processed.
Is Self-Assessment the same as a tax return?
Self Assessment is HMRC’s system for taxpayers to report relevant income and gains and assess their tax position. A Self Assessment tax return is the document submitted through that system. The form SA100 is the main return‚ with several supplementary forms‚ or pages‚ used to record income and gains depending on what is being declared․